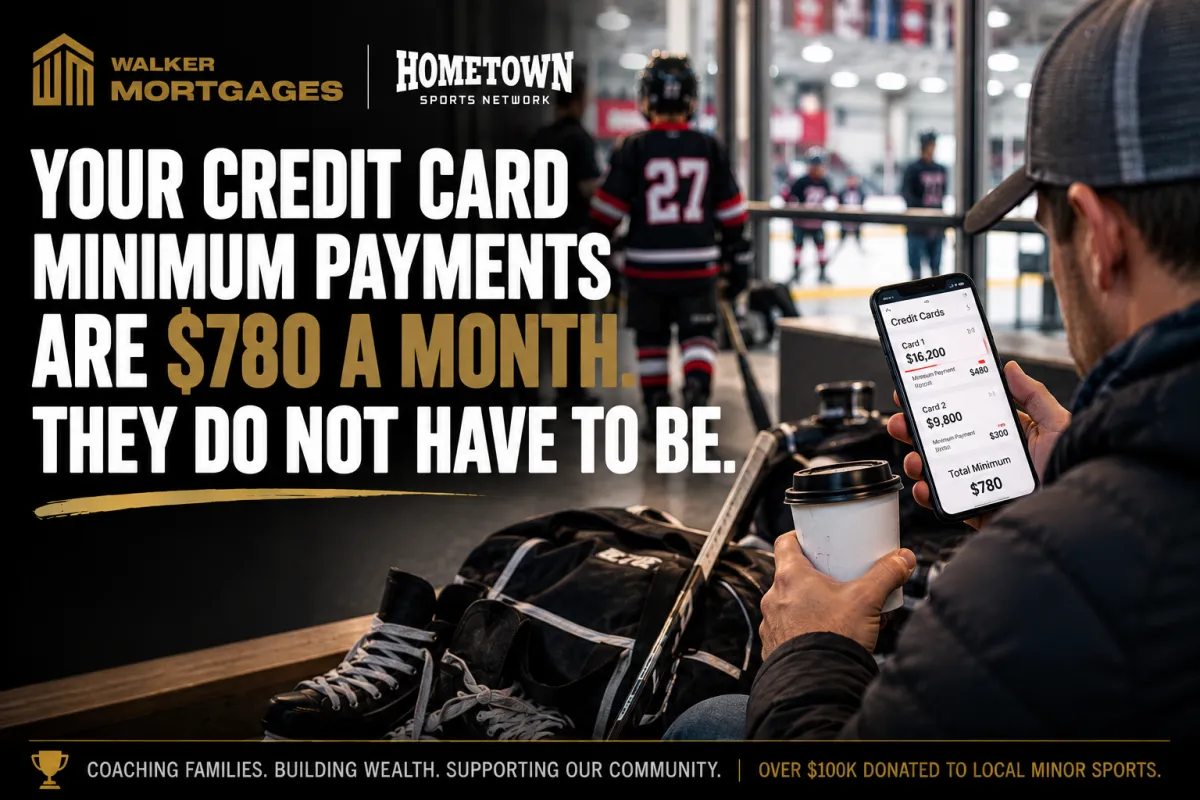
Your Credit Card Minimum Payments Are $780 A Month. They Do Not Have To Be.
You are standing in the rink lobby with a coffee in one hand and your phone buzzing in the other. The banking app notification. Minimum payment due. You open it without really wanting to see the number, and there it is, two cards, both looking a little worse than last month. Behind you, your son is already lacing up for a tryout that costs $175 just to skate in front of the coaches.
We get it. We are in the same rink lobbies, checking the same banking app, and plenty of us have felt that exact sink in our stomach before puck drop.
But here is what most families never hear. One hockey family I worked with found $640 back in their pocket this month. Not a lecture about spending less. Not someday. This month.
Where the money was actually going
This family was not reckless with money. Two kids, one in rep hockey and one in house league basketball, both parents working, doing what most families do. Somewhere along the way, two credit cards crept up. Card one sat at $16,200 at just under 23 percent. Card two sat at $9,800 at just under 20 percent. Together the minimum payments alone were about $780 a month, and that $780 barely moved either balance.
Here is the reframe that matters. The problem was never how much this family was spending. Cards like these are built to keep you paying and barely moving. The real problem was where that $26,000 was sitting.
The move
We rolled that $26,000 into their mortgage, at a mortgage rate instead of a credit card rate. Same debt. A completely different cost to carry it.
A card sitting near 22 percent is one of the most expensive kinds of debt a family can carry. A mortgage sitting around 4 percent is one of the cheapest. Same $26,000, borrowed by the same family, and the monthly bill is worlds apart just because of where it lives.
The math is not complicated. That $780 a month in minimum payments became about $140 a month folded into the mortgage. That is $640 back in their pocket. Not saved somewhere down the road. Sitting in the account this month.
That is a tryout fee. That is a tournament weekend. That is groceries without doing math in the parking lot first.
Why I do it this way
When I was coaching my own kids, I never wanted a number on a statement to be the reason we said no to a season. That has not changed. We never want you to say no to your kids and their sports because the debt is sitting in the wrong place.
Once we get the debt moved and the cashflow breathing again, I introduce families to the partners I trust, the people who help you keep growing and protecting what you have built. This is not a one time fix. This is the start of a relationship I plan to be around for a long time. Clients for life, not a closing date and a handshake.
Want to know your own number? Five minutes atadamwalkermortgages.com/monthly-payment-reset shows exactly what moving your debt could put back in your pocket, using your real numbers. No email gate. No sales pitch.
